


Suresh Manchanda
A New Era in India’s Sugar Market: Rising Prices, Imports and the Changing Face of Sugar Policy
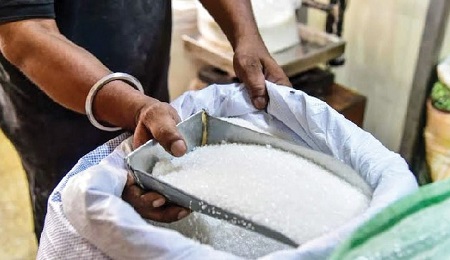
Until the end of July, sugar was trading at around ₹3G per kg in the domestic market. Then August arrived—and the sugar market suddenly turned into a national headline.
Within days, prices crossed ₹60 per kg. In some markets, prices reportedly surged by nearly 100%, crossing ₹80 per kg. The sudden price shock caught consumers, traders and policymakers off guard.
What makes the situation particularly interesting is the speed with which the policy narrative changed. Until July, India was allowing sugar exports under the prescribed quota. Within weeks, the government was compelled to open the door for imports and permit 1 million tonnes of sugar to be imported duty-free. Meanwhile, the Uttar Pradesh government launched raids against suspected hoarders and those allegedly involved in black marketing. Then came another debate. Was ethanol responsible for the surge in sugar prices?
Did lower sugar recovery from sugarcane reduce sugar production?
Did weather-related factors, including the impact of El Niño, contribute to the situation? Are sugar prices below ₹40 per kg actually viable for sugar mills and farmers?
Was allowing sugar exports a policy mistake? And perhaps the biggest question of all:
Have sugar prices peaked—or is another leg of the rally still possible?
These are not merely questions about the price of a household commodity. They go to the heart of India's sugar economy—an industry that connects farmers, sugar mills, ethanol producers, consumers, traders and government policy.
THE FIRST TRIGGER: SUPPLY UNDER PRESSURE
The domestic sugar market witnessed an extraordinary surge in August 2026.
According to government estimates, sugar production for the current season has been revised down from an initial projection of approximately 34.3 million tonnes to around 30.6 million tonnes.
Sugarcane diseases such as Red Rot and Top Borer have affected crop conditions in some important producing regions.
But production alone does not explain the sudden price movement.
India was also entering its most important consumption window of the year.
From August through November, the country moves through a series of major festivals—Ganesh Chaturthi, Dussehra and Diwali—when demand for sweets, confectionery and processed food products rises significantly.
THE FARMER'S DILEMMA
For sugarcane farmers, higher sugar prices are not necessarily bad news.
Farmers have consistently argued that sugar must command a remunerative market price if sugar mills are to remain financially capable of making timely payments for sugarcane.
A financially stronger sugar mill means better cash flow, faster cane payments and, ultimately, greater income security for farmers.
The question, therefore, is not simply:
“Why is sugar becoming expensive?”
It is also:
“What is the right price at which the entire sugar value chain remains financially sustainable?”
BUT IS INDIA REALLY SHORT OF SUGAR?
This is where the Sugar Saga becomes more complicated.
The Indian Sugar s Bio-energy Manufacturers Association (ISMA) has maintained that India is not facing an actual physical shortage of sugar.
According to the industry body, lower production is certainly one factor behind the tighter market. But bulk consumer stocking and speculative buying may also have contributed significantly to the sudden rise in prices.
ISMA has maintained that adequate stocks are available to meet domestic requirements.
The government, too, has said that sufficient sugar is available to meet domestic demand until the beginning of the new crushing season in October.
If that is the case, then the question becomes much more important:
Was the market rally driven by an actual shortage—or by the perception of a shortage?
WHY DID THE GOVERNMENT TURN TO IMPORTS?
The government's decision to permit duty-free sugar imports after nearly a decade was perhaps the most significant development of the entire episode.
It also raises an uncomfortable question:
How accurate and timely was the government's assessment of sugar stocks, consumption and market requirements?
The sudden transition—from permitting exports to facilitating imports—naturally raises questions about whether the available inventory and demand data were being captured accurately enough and early enough.
At the same time, there was no evidence of a complete collapse in domestic sugar production.
Industry sources also indicated that sugar recovery from cane had remained relatively strong in several areas.
If recovery was not the primary problem, and the new crushing season was only weeks away, then the magnitude and speed of the price rise inevitably raised another possibility:
Were stockists, large mills and speculative market participants amplifying the rally?
The answer may ultimately lie somewhere between fundamentals and market behaviour.
THE GOVERNMENT'S RESPONSE: BRING MORE SUPPLY INTO THE MARKET
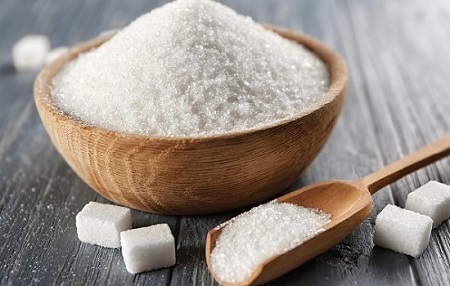
Once prices began rising sharply, the government's strategy became increasingly clear: More Supply → Better Market Sentiment → Lower Price Pressure → Consumer Relief The government moved on two fronts.
First, it permitted sugar imports.
Second, it tightened stockholding restrictions to prevent hoarding and artificial scarcity.
The objective was not merely to increase physical supply but also to change market psychology.
And market psychology matters.
Once traders and bulk consumers believe that supplies are becoming tight, stocking
increases. That stocking can itself push prices higher, creating a self-reinforcing cycle. The government appears to have attempted to break that cycle.
THE GOVERNMENT'S RESPONSE: BRING MORE SUPPLY INTO THE MARKET
The government has now moved beyond simply permitting imports.
It has also changed the way sugar is released into the domestic market.
FORTNIGHTLY QUOTA: A NEW SUPPLY MANAGEMENT SYSTEM
From September, the government is moving from a monthly sugar allocation system to a
15-day quota mechanism.
The objective is straightforward: ensure that sugar does not remain unnecessarily locked inside mills and reaches the domestic market faster and more consistently.
Under the new arrangement, sugar mills will have to sell at least 40% of their allocated quota during the first week, while the remaining quantity will have to be released during the following week.
Mills will also be required to dispatch the sugar within seven days of sale.
The government believes that this will allow it to monitor market supply more closely and respond more quickly to any emerging shortage.
If required, additional quota can also be released.
The broader objective is to prevent unnecessary accumulation of stocks and curb speculative activity.
STOCK VERIFICATION REVEALS ANOTHER SIDE OF THE STORY
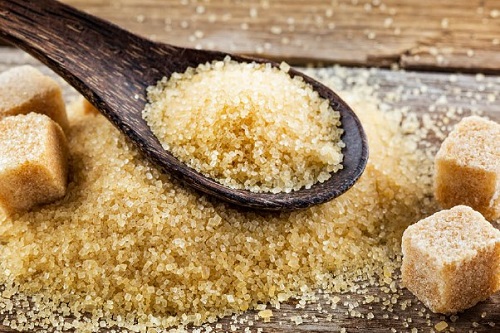
The government has also conducted stock verification across sugar mills. The inspections reportedly found that overall stocks were adequate.
However, some mills were found to be holding sugar stocks above their declared quantities.
At the same time, some mills had sold less sugar into the market than their allocated quota.
That matters because even when sufficient sugar exists physically, delayed release of stocks can create temporary tightness in the market.
This could partly explain how a market can simultaneously have adequate stocks and yet experience a sharp rise in prices.
The issue, therefore, may not always be “How much sugar does India have?”
It can also be:
“How much sugar is actually reaching the market—and how quickly?” That distinction could prove crucial in understanding the current Sugar Saga. THE SECOND BIG GOVERNMENT MOVE: STOCK LIMITS
Imports were not the government's only response.
To prevent hoarding and artificial scarcity, stockholding rules were tightened. From August 1, sugar dealers were subjected to a 400-tonne stock limit.
From September 1, bulk consumers will not be permitted to hold sugar stocks exceeding
15 days of their consumption requirement.
The government has also initiated physical verification of stocks held by sugar mills.
ETHANOL ENTERS THE STORY
No discussion of India's sugar market today is complete without ethanol. The Indian sugar industry is no longer simply a sugar-producing industry. Ethanol has fundamentally changed the economics of sugarcane.
Sugar mills now have an alternative route through which cane and sugar can generate revenue.
This has created a critical policy question:
Should the cane be used to produce sugar—or ethanol?
The industry's argument is straightforward.
If the government procurement price for ethanol is less attractive than the revenue a mill can generate from sugar, the mill has a natural economic incentive to maximise sugar production.
On the other hand, ethanol provides mills with diversification, supports the government's fuel-blending programme and creates an additional market for sugarcane-derived products.
THE IMPORT PARADOX
There is an interesting twist to the government's import decision.
The government has permitted imports of up to 1 million tonnes, but the economics of importing sugar have weakened as domestic prices have subsequently moderated.
Market participants now believe that actual imports could be significantly lower than the permitted quantity, with some estimates suggesting that only around 500,000 tonnes may ultimately be imported.
Why?
Because an importer will not buy expensive sugar overseas if the same commodity can soon be purchased more cheaply in the domestic market.
Some traders believe domestic sugar prices could eventually return towards ₹40 per kg, while ex-mill prices could move closer to ₹30 per kg.
If that scenario materialises, the commercial incentive to import disappears rapidly. This creates a classic commodity-market paradox:
The government may permit imports to cool prices—but falling prices may make those imports economically unnecessary.
The objective is clear:
Stop hoarding. Prevent artificial scarcity. Curb speculative stocking.
THE GLOBAL SUGAR STORY
India's Sugar Saga is not an isolated domestic story. The global sugar market is also sending important signals.
According to the Government of India, the global sugar market could face a deficit of approximately 3.3 million tonnes in 2026-27.
International prices have responded.
Sugar prices were around $474 per tonne on June 30, 2026, rising to approximately $552 per tonne by August 20—an increase of more than 16% in less than two months.
For India, this matters.
If domestic supplies tighten sufficiently to require imports, the international market will determine the cost of that additional supply.
That means the Indian sugar market cannot be viewed in isolation.
Brazilian production, global exports, weather, currency movements and international sugar prices can all influence India's domestic market.
OCTOBER: THE REAL TEST
The biggest turning point could come in October.
The government has advised sugar mills to begin crushing from October 15, 2026.
The expectation is that sugar production could exceed 1 million tonnes in October, compared with the normal monthly production level of around 300,000–400,000 tonnes.
If the new crushing season begins on schedule and sugarcane availability remains healthy, the supply situation could improve rapidly.
And that could change market sentiment almost overnight. The critical question is therefore:
Will the August-September price rally fade once fresh sugar begins entering the
market in October?
Or will production estimates be revised lower again?
That is the question the market will be watching most closely.
WHAT WILL DETERMINE THE NEXT MOVE IN SUGAR PRICES?
The next phase of the sugar market will depend on six major factors.
Will the government continue with imports, stock limits and market interventions—or gradually withdraw these measures as domestic supply improves?
(The content of this article reflects the views of writer and contributor, not necessarily those of the publisher and editor. All disputes are subject to the exclusive jurisdiction of competent courts and forums in Delhi/New Delhi only)











Leave Your Comment