


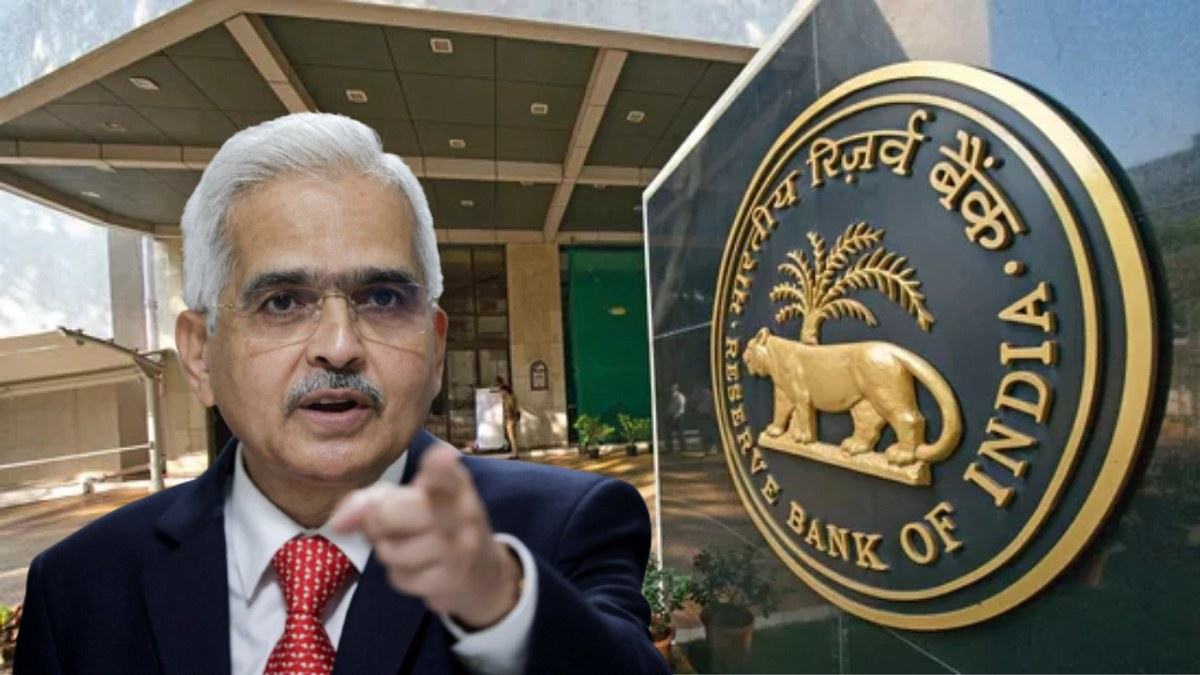
In a significant move to address concerns over the rapid growth of unsecured loans in the Indian financial landscape, the Reserve Bank of India (RBI) has recently implemented measures aimed at bringing more prudence and stability to the lending sector. The decision comes amidst rising worries about the potential risks associated with unsecured loans, which have been witnessing a substantial uptick in recent years. This article explores the steps taken by the RBI and analyzes the potential effects on both banks and non-banking financial companies (NBFCs).
The RBI's recent intervention involves a combination of regulatory changes and policy adjustments designed to tighten the norms surrounding unsecured loans. One of the key measures taken by the central bank is the revision of risk weights assigned to different categories of loans. The risk weight determines the amount of capital that banks and NBFCs need to set aside against their loan portfolios, acting as a crucial factor in maintaining financial stability.
Under the revised framework, the RBI has increased the risk weights on unsecured loans, making it more expensive for financial institutions to extend such credit. This move is expected to act as a deterrent for lenders and encourage them to adopt a more cautious approach when dealing with unsecured loan products.
Banks, being primary lending institutions, are likely to experience a direct impact from the RBI's measures. The increased risk weights will necessitate banks to allocate a higher amount of capital for their unsecured loan portfolios. This, in turn, may lead to a reduction in the overall availability of unsecured credit, as banks may choose to limit exposure to such loans to maintain their capital adequacy ratios.
While this move may contribute to mitigating the risks associated with unsecured loans, it could also have repercussions on consumer spending and economic growth. With reduced access to unsecured credit, consumers may find it challenging to finance personal expenditures, impacting sectors such as retail, travel, and hospitality.
Non-banking financial companies, which often play a significant role in providing unsecured loans to individuals and businesses, are also set to be affected. The increased cost of capital due to higher risk weights may compel NBFCs to reevaluate their lending strategies. This could result in a shift towards more secured lending or the introduction of stringent eligibility criteria for unsecured loans.
The RBI's measures might lead to increased competition among NBFCs for secured lending opportunities, potentially influencing interest rates in that segment. Furthermore, smaller NBFCs with limited capital reserves may face greater challenges in adapting to the new regulatory environment, possibly leading to market consolidation.
The Reserve Bank of India's decision to address the fast growth of unsecured loans reflects a proactive stance in maintaining the stability of the financial sector. While the increased risk weights aim to instill prudence among lenders, it is essential to monitor the broader impact on economic activities and credit availability.
Banks and NBFCs will need to adapt to the revised regulatory framework, recalibrating their lending practices and strategies. As the financial landscape evolves in response to these changes, the effectiveness of the RBI's measures in balancing risk and economic growth will become clearer in the coming months.










Leave Your Comment